



The Central Bank of Nigeria (CBN) has reopened access to Open Market Operations (OMO) securities for individuals, companies, and non-bank financial institutions, providing Nigerians with another option for investing in short-term securities.
This decision reverses the restriction that was implemented in October 2019, when the CBN prohibited local individuals and corporations from participating in OMO auctions. At that time, the measure aimed to reduce pressure on OMO auctions and restore the instrument to its primary role as a monetary-policy tool.
Under the new arrangement, individuals and companies can participate in both the primary and secondary OMO markets through Deposit Money Banks. The reopening comes amid strong investor demand for short-term fixed-income investments.
In a recent OMO auction, investors submitted approximately ₦4.93 trillion in bids for ₦600 billion initially offered by the CBN. The 103-day OMO bill cleared at a rate of 20.39%, while the 138-day bill cleared at 20.01%. Ultimately, the CBN allotted around ₦2.60 trillion.
For investors looking to keep their money invested for a few months, returns above 20% make OMO an attractive option. But what exactly is OMO, and what does its return to retail investors signify for Nigeria’s expanding digital investment industry?
What OMO is and why its 20%+ yield matters
OMO stands for Open Market Operations.
In simple terms, OMO is a method used by the Central Bank of Nigeria (CBN) to control the amount of money circulating within the banking system. When the CBN wants to withdraw excess money from the financial system, it sells OMO bills. Investors purchase these securities, and the money used for the purchase is effectively removed from circulation for the duration of the investment.
The CBN is both the issuer of OMO bills and the institution that uses them as a monetary policy tool. This distinguishes OMO from Treasury bills, even though they may appear similar to an ordinary investor.
Treasury bills are issued by the Federal Government to raise funds for government financing, whereas OMO bills are issued by the CBN primarily to manage liquidity and support monetary policy objectives. The CBN has clarified that OMO and Treasury bills serve different purposes, have different issuers, and possess different structures.
This distinction is significant because the CBN does not issue OMO bills simply when it needs to raise money for government spending; it utilises this instrument based on prevailing conditions in the financial system.
For investors, the concept is straightforward: If you have ₦1 million that you don’t need immediately, you can invest it in an eligible short-term security, hold it until maturity, and receive the agreed-upon return.
The high yields from recent OMO bills are attracting retail investors. In a recent auction, a 103-day bill had a rate of 20.39%, and a 138-day bill had a rate of 20.01%. However, these figures are annualised yields, meaning that the actual profits depend on how much you invest and for how long.
For instance, if you invest ₦1 million at a 20% yield for about 100 days, you won’t earn ₦200,000; your return will be based on the specific investment duration.
It’s also important for investors to compare OMO with other investment options rather than just choosing the highest rate they see. Treasury bills are a significant alternative; for example, during an August auction, ₦4.4 trillion was bid for ₦700 billion available. The rates were 16.30% for a 91-day bill, 16.50% for an 182-day bill, and 17.59% for a 364-day bill, showing that OMO rates were notably higher.
Additionally, there are money market funds that invest in short-term securities. Some of these funds are generating returns around or above 18%, with some exceeding 20% this year. Therefore, OMO is entering a market where Nigerians have multiple options to earn better short-term returns.
Where Nigerian fintechs come in
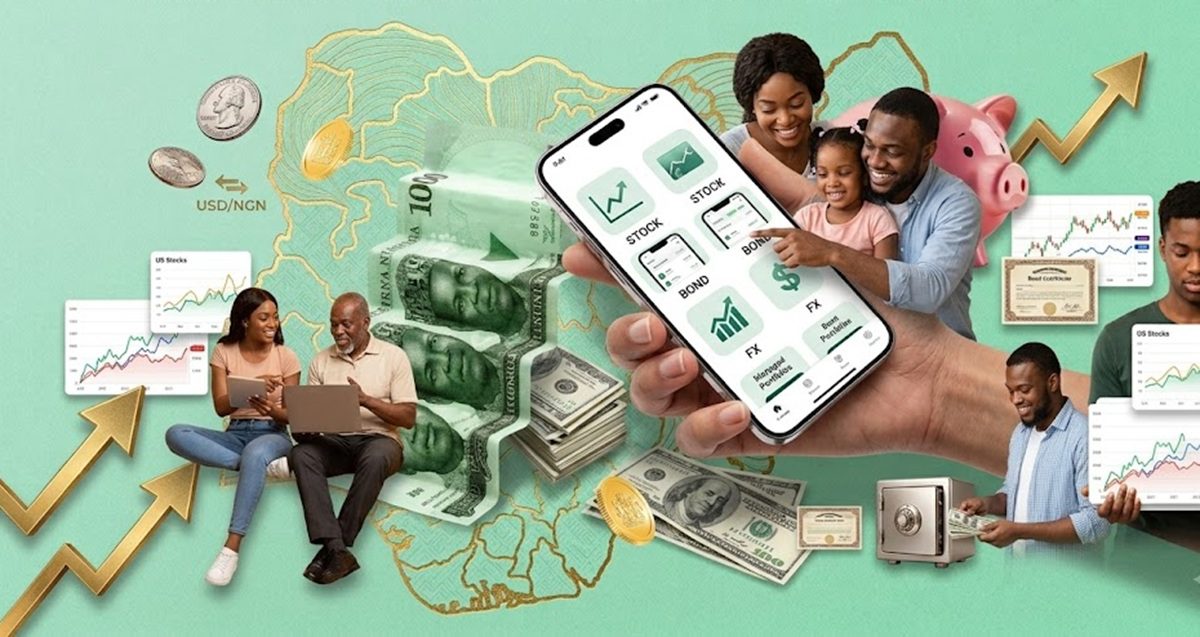
Platforms like i-invest have made it easy for users to access Treasury bills and various fixed-income products right from their phones. They started with Treasury bills and stocks but have since expanded to include mutual funds, ETFs, and other financial services.
Similarly, Cowrywise enables users to automate their savings and invest in mutual funds through its digital platform, operating under a licence from the Securities and Exchange Commission (SEC). Other apps like Bamboo and Risevest further facilitate investment by making financial markets accessible at users’ fingertips.
With the reopening of Open Market Operations (OMO) to individuals, fintech companies and digital investment platforms might explore this new opportunity. However, it’s important to note that not all fintech apps can immediately offer OMO bills. These securities function within a regulated financial market, and individual participation is conducted through Deposit Money Banks. This means that fintechs need the right regulatory framework and partnerships to integrate OMO access into their services.
Similar read: CBN opens second regulatory sandbox cohort to VASPs, stablecoin startups and fintechs
Platforms that already have ties with banks or licensed market operators may have a competitive edge. Instead of requiring users to understand how OMO auctions work, these platforms could streamline the process by showing available tenors, explaining yields, displaying minimum investment amounts, handling applications, and allowing customers to track their investments until maturity. This approach mirrors what fintechs have successfully done with other financial products.
Could OMO become the next product on investment apps?
The opportunity is clear. A Nigerian investor can open an investment app and choose between a 17% Treasury bill, a money-market fund, or an OMO bill with a higher yield, allowing for easy comparison of returns, risks, and liquidity.
However, fintechs must adhere to regulatory requirements set by the SEC, which mandates that operators providing capital-market services be registered. If they enter the OMO distribution space, aspects like regulation, custody, and investor protection will be crucial.
The most significant change is choice: investors now have OMO as an option alongside Treasury bills and fixed deposits. Yet, a higher yield doesn’t guarantee it’s the best choice for everyone; factors like investment duration, access before maturity, and fees must be considered.

If OMO consistently offers better yields, it could shift competition in short-term investments, attracting more money and influencing future yields based on the CBN’s issuance strategy.
For fintechs, the challenge is to simplify access to OMO as effectively as they have done with other financial services. If successful, OMO could become a familiar investment choice for Nigeria’s retail investors.
See also: Why Nigeria’s power crisis is the hidden reason CBN can’t hit zero failed transactions by 2028
