


For a decade, Flutterwave has built its business around helping money move between people, businesses and countries. Now, the Nigerian fintech wants to do something more ambitious: help customers store, grow and borrow money on the same financial infrastructure.
Speaking at Moonshot by TechCabal in Lagos on Wednesday, October 28, Flutterwave CEO Olugbenga “GB” Agboola said the company’s next phase would focus on building a broader financial operating system, moving beyond payment processing into banking, lending, investments and stablecoin-powered cross-border transfers.
“If you can trust us with your payment, it’s a much easier sell to actually keep the money for you,” Agboola said.
The shift follows Flutterwave’s acquisition of open-banking startup Mono in January and its acquisition of a national microfinance banking licence in April. The licence allows Flutterwave to accept deposits and lend directly within the regulatory limits of its banking category.
At the conference, held at the National Theatre under the theme “Courage and Conviction: Building for a New World”, Agboola explained that the decision was not simply about becoming a bank. It was about having greater control over the infrastructure that customers depend on.
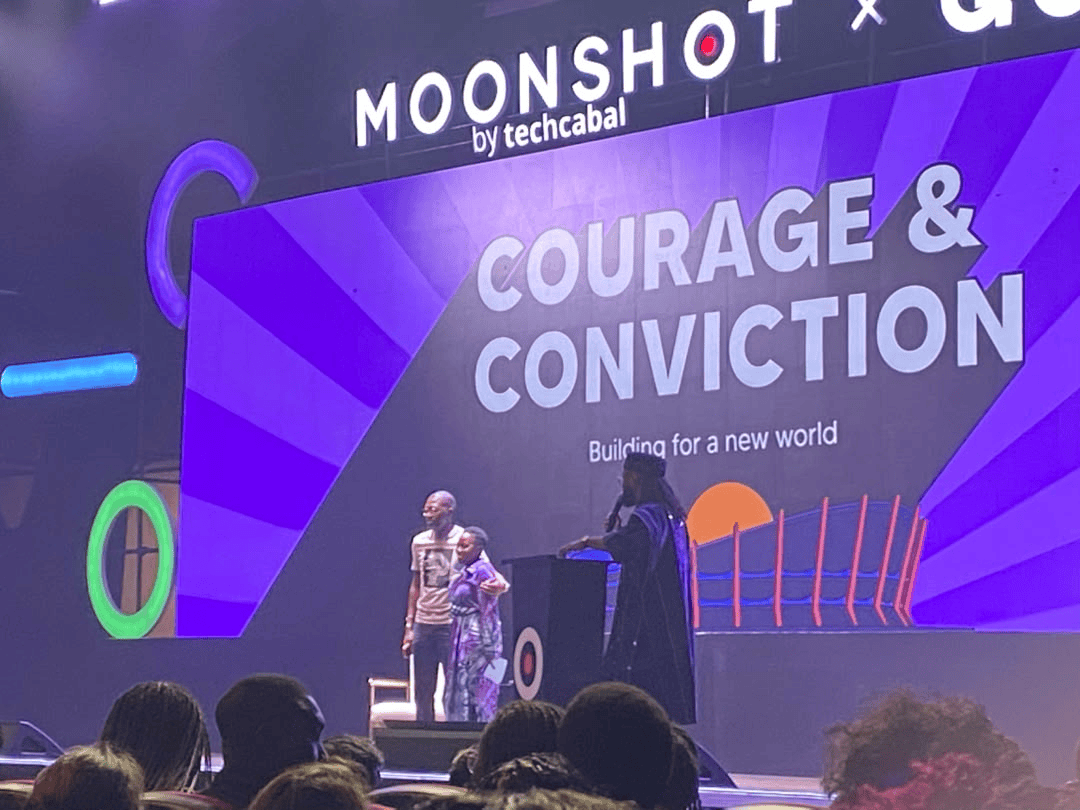
GB on why Flutterwave wants to become a bank
Flutterwave has spent the past decade connecting payment systems across Africa. Although countries such as Nigeria, Ghana and Kenya have developed their own payment infrastructure, moving money across their borders remains complicated.
Agboola said Flutterwave had made significant progress connecting these systems, but moving money alone was not enough. Businesses also need places to keep their earnings, access credit, pay suppliers and invest.
The company’s reliance on partner banks has also created a reliability problem. When a partner bank experiences downtime or schedules maintenance, services that depend on it can be disrupted.
“You cannot provide an accurate payment experience if you don’t control the entire stack, or at least a big piece of the stack,” he said.
The banking licence gives Flutterwave greater control over parts of that infrastructure. However, it does not mean the company will stop working with banks. Agboola said Flutterwave would continue partnering with financial institutions while deciding which parts of its operations it needs to control directly. The aim is to reduce disruptions and give customers more financial services through one platform.
Agboola illustrated the plan with a fashion business operating in Accra or Nairobi. Beyond accepting payments, such a business needs to pay suppliers, manage its cash, finance operations and move money across borders.
Flutterwave wants to bring these activities together. Agboola said businesses could already use its services to make certain international payments, access investment products and, through its banking operations, access deposits and lending.
Similar read: Fintechs are buying up banks; what happens when the startups become the banks?
He also pointed to payments to Chinese suppliers as an example of how the company wants to simplify trade. Nigerian businesses can pay eligible Chinese suppliers in naira through Flutterwave’s infrastructure, reducing the need to source dollars for those transactions. The company is also betting on stablecoins, digital tokens designed to maintain a relatively stable value, often by tracking a currency such as the US dollar.
Agboola said Flutterwave had deployed stablecoin capabilities across its business and consumer products to support compliant transfers. He described the technology as an important option for businesses whose suppliers want faster settlement than traditional international bank transfers can offer.
Rather than expand indiscriminately, Flutterwave plans to develop services around specific industries and their needs. Agboola named fashion and e-commerce as areas where the company could build more specialised financial products, including escrow services that help protect buyers and sellers during transactions.
Ghana and Kenya are also important markets for its plans to expand beyond payments into banking-related services, he said.
Lending brings opportunity and risk
Moving into lending could create another source of revenue for Flutterwave, but Agboola described a gradual approach rather than an immediate push into broad consumer lending.
The company currently provides liquidity to payment businesses, including by advancing funds so payouts can happen before the money arrives from another party. It also plans to provide secured and working-capital financing to businesses and fintech companies.
Over time, it wants to explore lending to businesses in sectors such as manufacturing, where short-term financing could help companies meet operational needs.

Flutterwave is also studying transaction data to identify unmet demand for credit. Agboola cited payment data in which around 30% of attempted transactions in a particular set of observations failed because of insufficient funds. He said the pattern could point to demand for consumer lending, provided the company can assess borrowers’ ability to repay.
However, he acknowledged that turning these observations into lending products requires careful underwriting and risk assessment. A failed payment does not automatically make someone a suitable borrower.
Trust will matter as much as technology
The expansion also raises questions about how Flutterwave will protect customers’ money as it takes on more banking responsibilities.
Asked what the company had changed internally to earn trust with customer deposits, Agboola initially answered, “Nothing.” He then explained that Flutterwave had built its infrastructure around trust from the beginning, but was now working harder to communicate what it does, how its systems operate and how it supports businesses.
That explanation places greater weight on transparency as Flutterwave moves into services where customers entrust it with money they may need to access at any time.

The company’s next phase will depend not only on whether it can connect payments, deposits, credit and international transfers, but also on whether it can manage the risks that come with those services.
Flutterwave wants to become more than the company that moves money between businesses and their customers. Its ambition is to become part of the infrastructure those businesses rely on to operate and grow. Whether it can deliver that promise consistently will determine how far its banking strategy takes it.
Read also: VitalSwap adds US-to-Africa remittances and stablecoin checkout
