


Nigeria’s crypto economy shrank in the year to June 2026, while South Africa’s grew by half. The easy conclusion is that Nigerians have lost their appetite. Experts believe the data supports something else: stablecoin adoption is deepening. In one market, it is adding volume; in the other, it is reshuffling it.
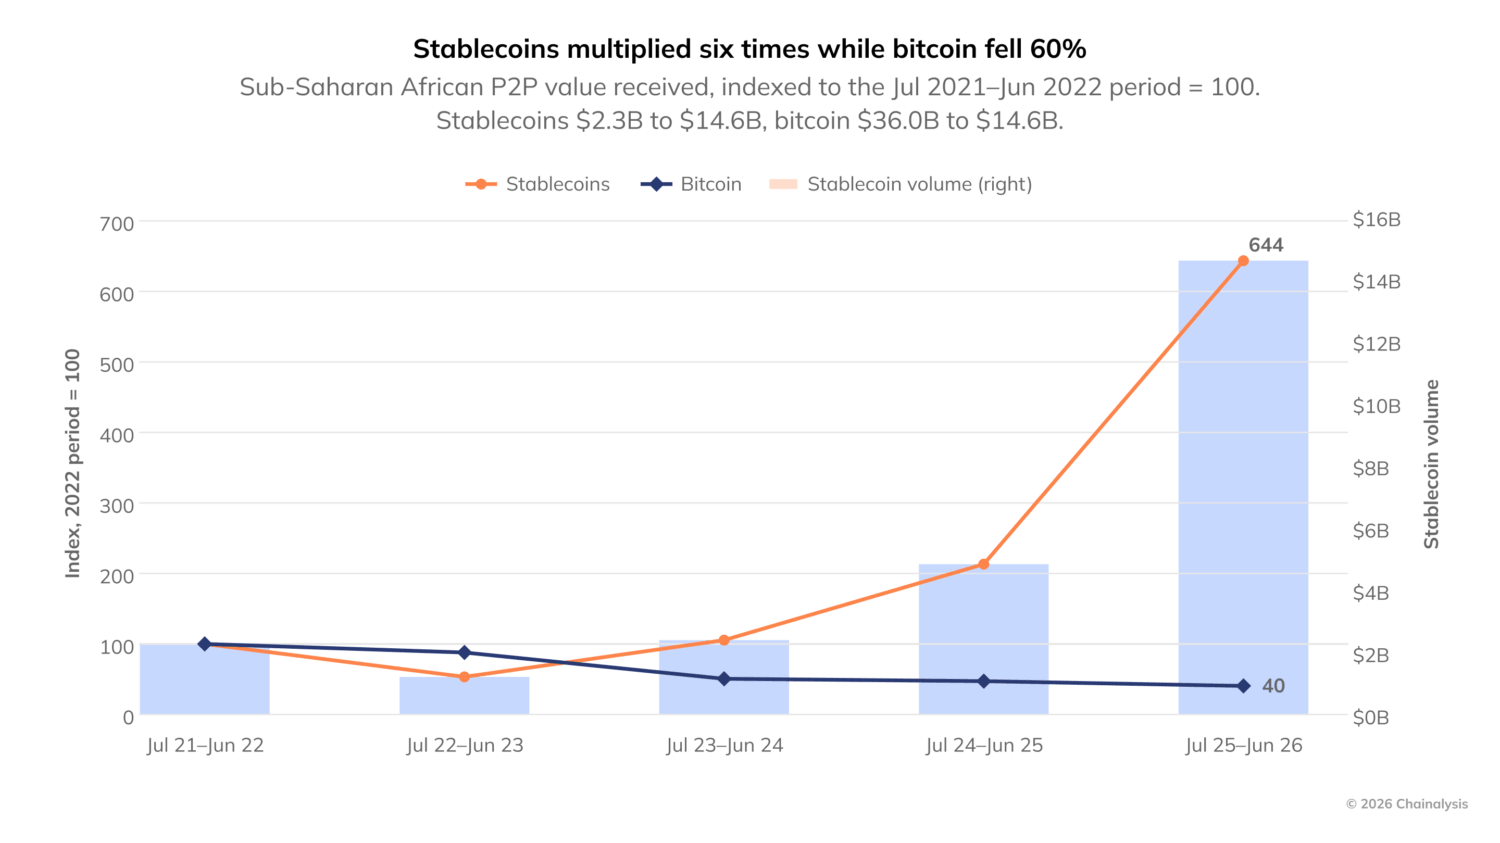
According to Chainalysis’ 2026 Geography of Cryptocurrency Report, Sub-Saharan Africa received $101 billion in on-chain value between 1 July 2025 and 30 June 2026. The region grew by 13.4% in that period, making it the fastest-growing crypto region in the world, even though it remains the smallest. Peer-to-peer stablecoin inflows across the region grew more than sixfold, from $2.3 billion in 2022 to $14.6 billion in 2026, while Bitcoin inflows fell 60%, from $36 billion to $14.6 billion.
To understand why traditional lenders and informal merchants are converging on the same rails, Technext spoke with Nzube Ezudo, a former corporate banker who now leads Superteam Nigeria, the Nigerian chapter of the global Superteam talent network in the Solana ecosystem.
One continent, two speeds of formalisation
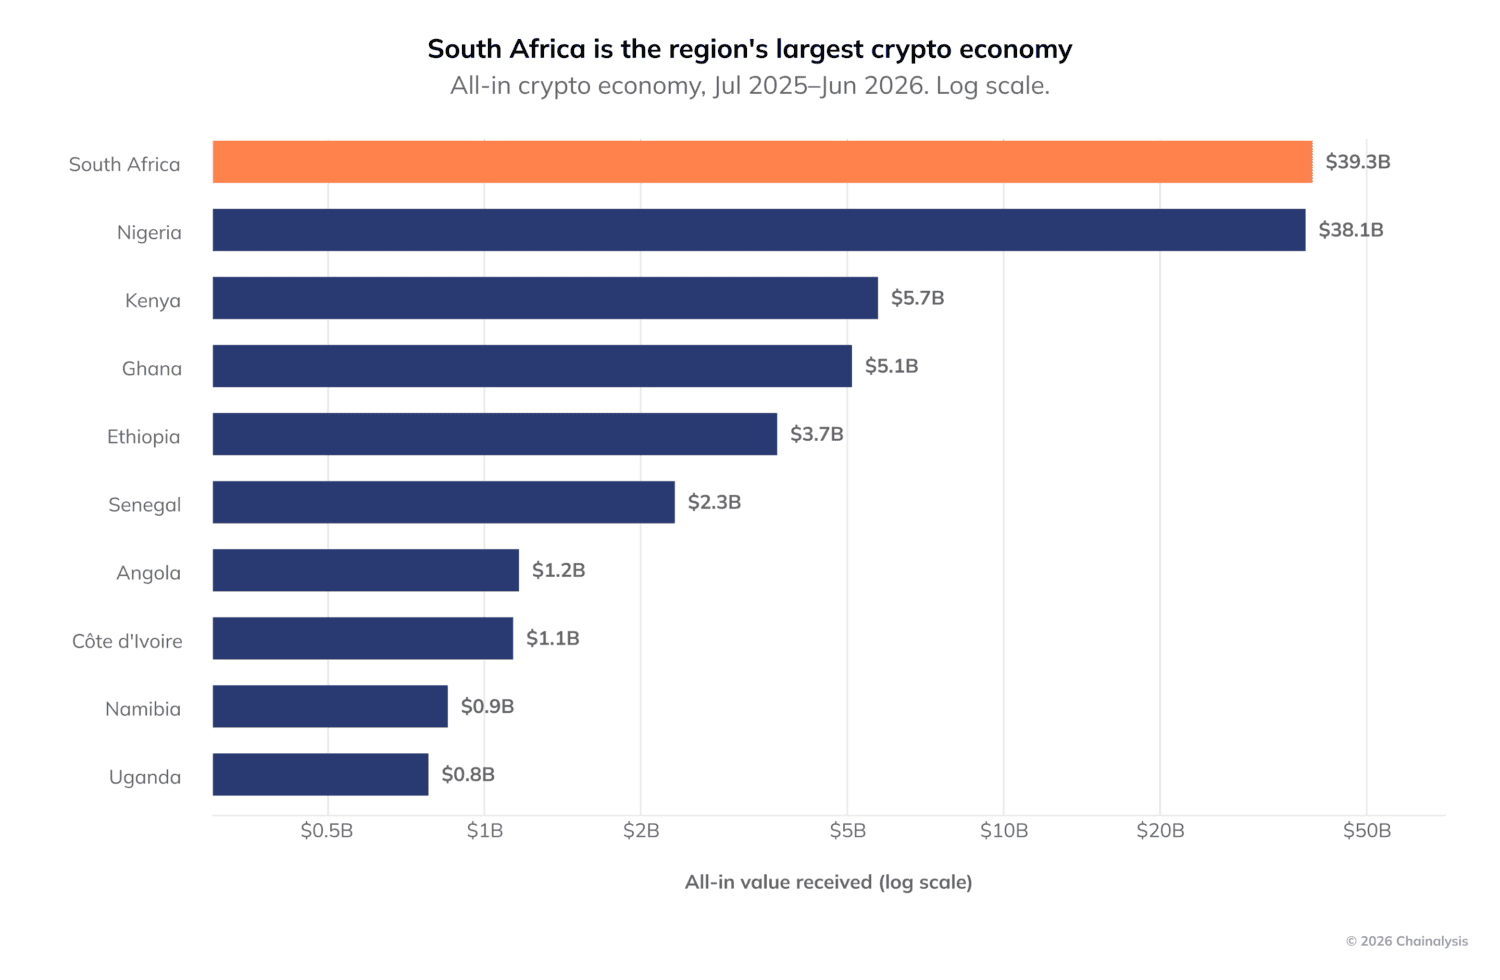
South Africa and Nigeria together account for more than three-quarters of Sub-Saharan Africa’s crypto activity, yet the two heavyweights moved in opposite directions. South Africa’s market expanded by 52% to $39.3 billion, helped by $8.34 billion in domestic business-like payments, which grew faster than its $1.29 billion in institutional inflows. Nigeria recorded $38.1 billion, a decline of 3%, even as it placed third on the Chainalysis grassroots adoption index and its users sent $25.2 billion to crypto services.
Ezudo argues that the split reflects regulatory sequencing, not waning Nigerian demand. South Africa has treated crypto as a regulated financial product for a few years, he says. Exchanges are licensed, banks will deal with them, and businesses can run crypto through their books without fear.
“When institutions and merchants get that comfort, volume follows. That is what a 52% jump looks like,” he says. “Nigeria’s drop is not a loss of interest. Nigerians are still among the most active crypto users in the world. What changed is the urgency and the routing.”
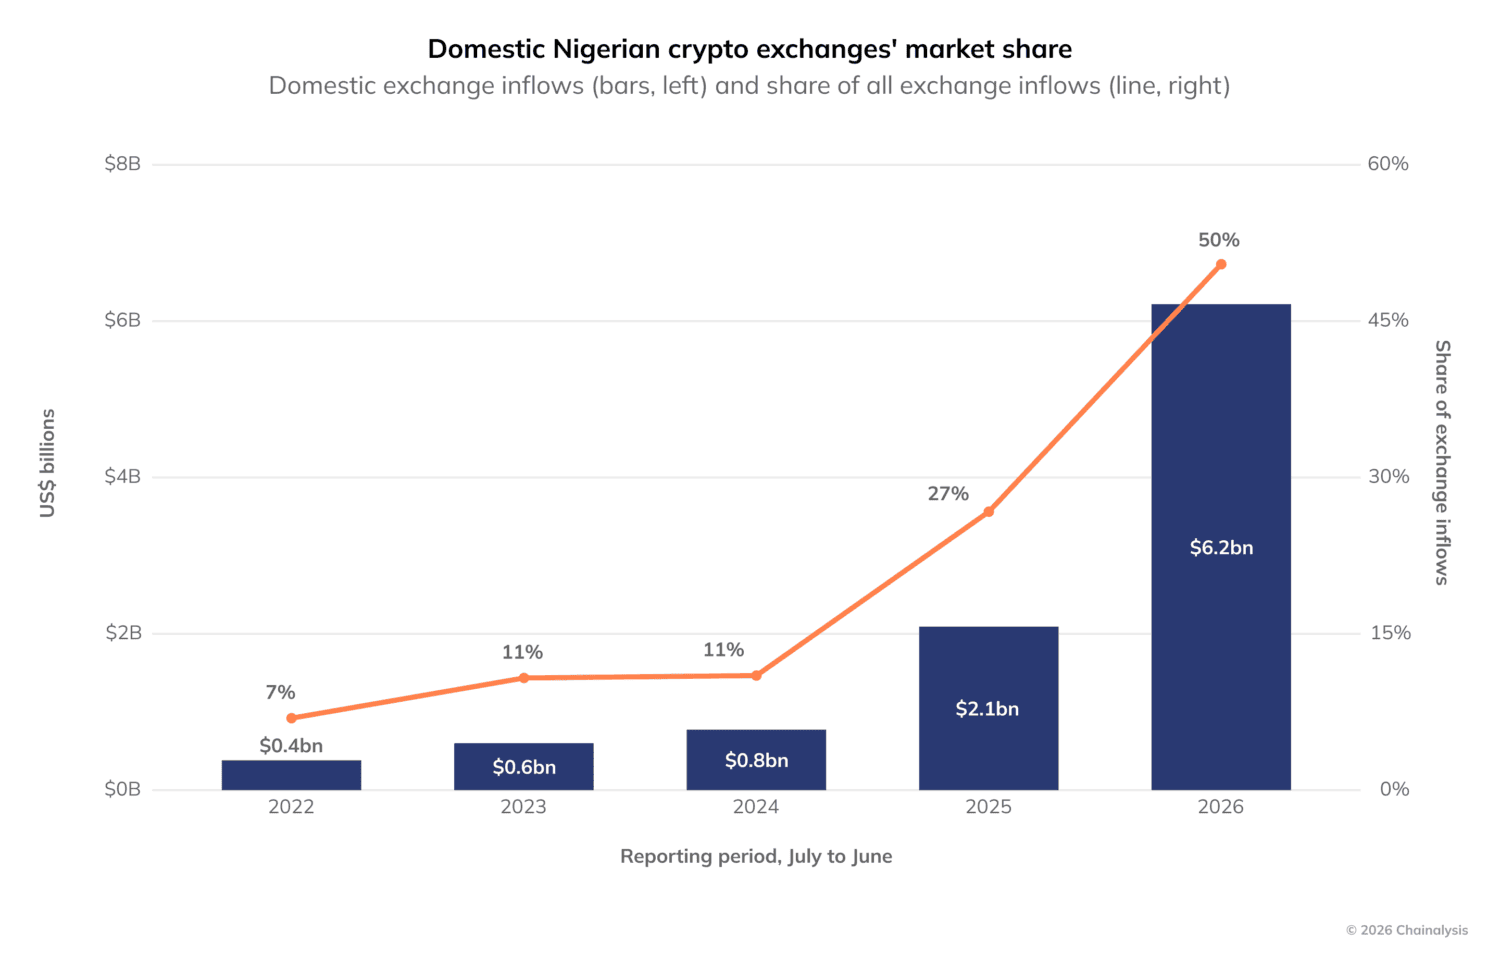
Compared with the foreign exchange shocks of 2024, a steadier naira cooled panic-driven hedging. At the same time, tighter regulation and tax reporting reshaped how value moves. Decentralised exchange activity fell by 45% and cross-border peer-to-peer flows fell by 17%, while domestic centralised exchanges now take half of Nigeria’s centralised exchange inflows, up from 27% in 2025 and just 7% in 2022.
Some of that shift is real and healthy, Ezudo says, because licensed local platforms offer better naira liquidity and faster payouts. He suspects the rest has moved out of public view, into over-the-counter desks, merchant networks settling off-chain, and WhatsApp and Telegram trading groups.
“In South Africa you are seeing formalisation that adds volume. In Nigeria you are seeing formalisation that reshuffles volume,” he says. “Over time, I expect Nigeria to see the same institutional lift that South Africa is enjoying now. The goal should be to make the regulated route so cheap and easy that there is no reason to leave it.”
There is one Nigerian exception worth noting. At the regional level, stablecoins are doing more of the work, but Chainalysis found that Bitcoin still accounted for 92% of Nigeria’s small domestic wallet transfers below $10,000, or $923 million of $1 billion, compared with 22% in the rest of Sub-Saharan Africa. Nigeria’s formal services are growing, but its P2P habit remains distinctly Bitcoin-driven.
Will the Ghana and Senegal surges last?
Outside the two giants, smaller West African markets posted dramatic gains. Ghana’s crypto economy grew by 80% to $5.1 billion, and Senegal’s surged by 215% to $2.3 billion. Ezudo shares some of the scepticism those numbers invite.
“Percentages from a small base tell you less than people think,” he says. “Senegal at $2.3 billion is still a young market, so a few active corridors or OTC desks can move the number a lot.”
Yet the drivers are not only speculative. Ghana has spent two years building a regulatory framework, and once businesses know the rules, they start moving real payments. Senegal sits inside the CFA franc zone, so its growth is driven less by currency collapse and more by demand for cheaper, faster payments across West Africa and with the diaspora.
“My test for sustainability is simple: does the volume survive a quiet market? If these numbers hold while prices go sideways next year, it is adoption. If they fade, it was a moment,” Ezudo says. “I am leaning towards adoption because stablecoins, not volatile tokens, are doing more of the work.”
Savings first, settlement fastest
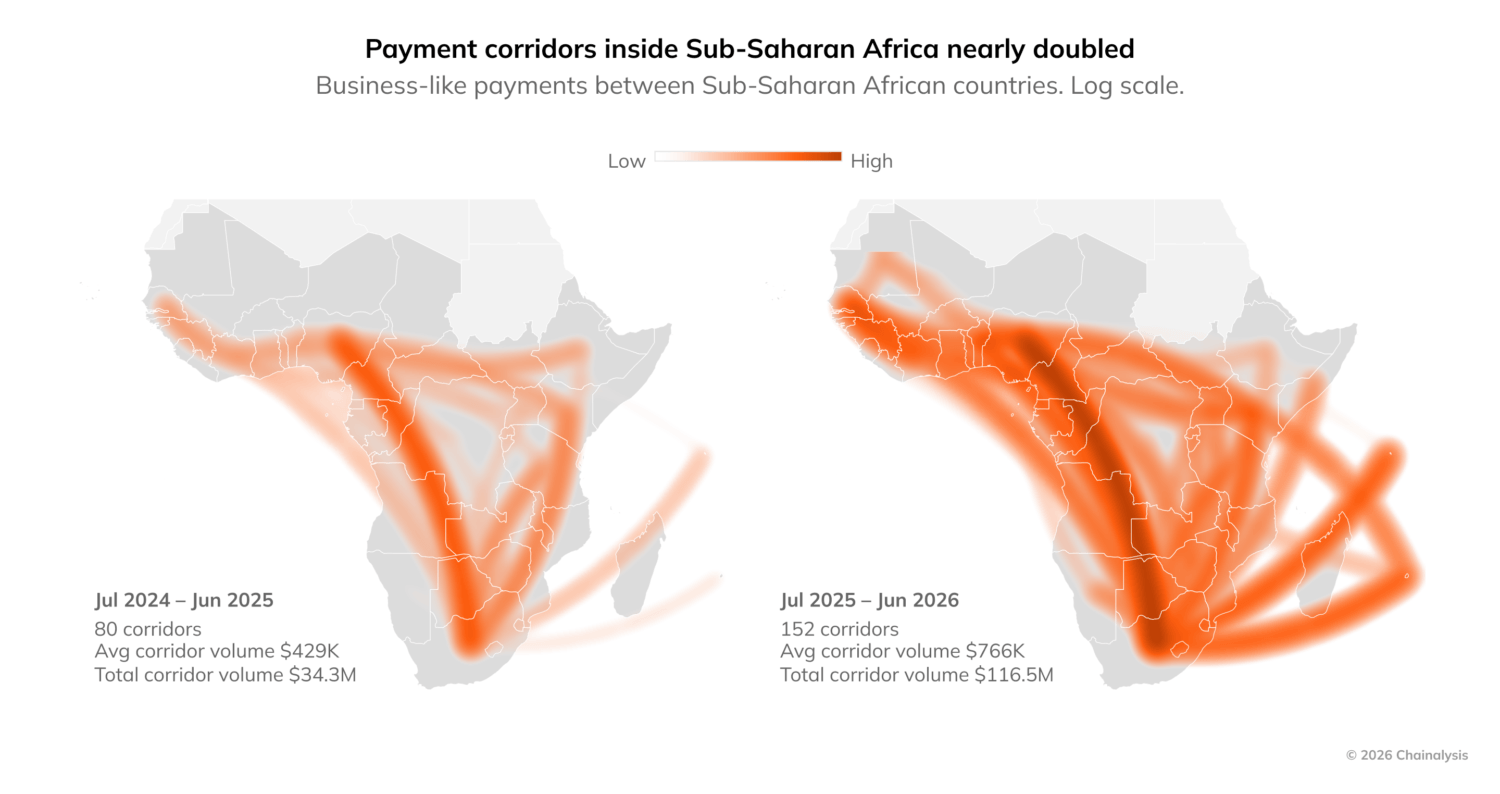
Across the $101 billion regional market, most volume is still savings and value preservation, Ezudo concedes. Merchant settlement is the smaller slice, but it is the fastest-growing one, and it is where he believes the story changes from crypto as a savings account to crypto as a payment rail. Active intra-African crypto payment corridors nearly doubled in a year, from 80 to 152, and their total value more than tripled, from $34.3 million to $116.5 million.
“When your currency loses a large share of its value within a couple of years, holding dollars on-chain is a rational decision, not a speculative one,” he says. “I would also push back on the term capital flight. A small business protecting its working capital is not fleeing. It is surviving.”
On-chain data cannot settle how much of that corridor volume is trade and how much is family remittance, and Ezudo does not pretend otherwise.
“A wallet does not announce whether it is a trader in Kano paying a supplier in Accra or someone sending money home to family,” he says. “My read from the ecosystem is that most of it is still small businesses and informal traders using P2P rails, which blurs the line between remittance and trade. That is actually the story: the informal economy is where intra-African trade lives, and it is adopting first.”
Doubling that volume again will not be a blockchain problem, he argues. It needs three fixes:
- Local off-ramps: cheap, instant conversion into mobile money and bank accounts in every corridor, not just the big four markets.
- Business tooling: invoicing, reconciliation and receipts that a business’s accountant and tax authority will accept.
- Compliance built in: identity and travel rule checks that let banks and regulators get comfortable without killing speed.
“Chains like Solana already settle in under a second for a fraction of a cent,” Ezudo says. “The blockchain is not the bottleneck anymore. The last mile is.”
Why banks followed their customers into stablecoins
Three things broke the dam for traditional finance, Ezudo says. First, the customers left. Businesses were already settling invoices in USDT and USDC because correspondent banking was slow, expensive and shrinking, as global banks pulled out of African corridors. Second, regulation arrived, and compliance teams stopped saying no by default. Third, the global signal changed: once Visa, major United States banks and payment companies began building on stablecoins, the reputational risk of touching them flipped into a risk of being left behind.
“Banks watched fee income walk out the door,” he says. “Dollar stablecoins are the compromise because they solve the problem banks actually have, which is dollar liquidity and settlement speed, without asking anyone to take a view on Bitcoin’s price. To a bank’s risk committee, a regulated, fully reserved dollar token looks like a faster payment instrument, not a speculative asset. That is a conversation they can have.”
The clearest marker of that shift came on 1 September 2026, when 21 global financial institutions, including Bank of America, Citi and Goldman Sachs, committed to establish a company to issue a United States dollar stablecoin, targeted to reach the market in the first half of 2027. Standard Bank, Africa’s largest lender, is the only African institution in the group. Within the region, Chainalysis also notes growing experimentation with local currency stablecoins in South Africa, Ghana, Kenya and Tanzania, including a cedi-backed model being examined by the Bank of Ghana, which would let beneficiaries receive cedis through bank accounts or mobile money without holding crypto themselves.
None of this means banks will swallow the remittance market. Diaspora communities sent $888 million to the region through crypto remittances during the period, $645 million of it from North America, while the World Bank put the average cost of sending $200 to Sub-Saharan Africa at 7.9 per cent, the highest of any region. Ezudo expects convergence, not replacement: banks as the licensed rails and liquidity partners, and startups keeping the customer.
“A bank running a pilot does not change its cost structure or its customer experience overnight,” he says. “The startups at risk are the ones whose only edge was regulatory arbitrage. The ones with a real product will be fine.”
Self-custody is a memory, not an ideology
Even as institutions enter, personal wallets received 32.3% of all value entering Sub-Saharan Africa, the highest share in the world, and 70.9% of that value arrived through cross-border P2P transfers. Ezudo reads that as self-defence learned from experience, not as evasion.
“Many people here have lived through frozen accounts, sudden withdrawal limits, exchange shutdowns, or a payment provider being banned overnight,” he says. “After that, holding your own keys is not ideology. It is common sense. That is a payment behaviour, not a hiding behaviour.”
His advice to builders is not to force users back into custodial accounts but to make self-custody safer and easier, with recovery options, better wallet design and compliant on-ramps.
Central banks are right to worry, Ezudo says. If a large share of savings and trade moves into dollar tokens, monetary policy loses some of its reach. Nigeria moved to coordinate its rules in July 2026, when President Bola Tinubu signed an Executive Order on Virtual Asset Coordination, creating a council chaired by the Central Bank of Nigeria to harmonise how regulators treat virtual assets, including stablecoins.
“But the stablecoins are a symptom, not the cause,” he says. “People reached for dollars when local currency was unstable or hard to move. They were doing it with cash dollars and parallel markets long before crypto. Banning the tool does not remove the demand. It just pushes it somewhere less visible.”
His prescription is to regulate stablecoin activity, encourage local currency stablecoins for domestic and regional trade, and plug these rails into national payment systems.
“The best defence of the naira or the cedi is a stable currency that is easy to use,” Ezudo says. “If central banks get that right, stablecoins can carry their currencies instead of replacing them.”
