



Africa doesn’t trade with itself, and that failure has quietly become one of the biggest opportunities in global finance. Fragmented currencies, punishing transfer fees and banks that treat cross-border payments as an afterthought have left the continent searching for solutions. Increasingly, that fix looks like stablecoins.
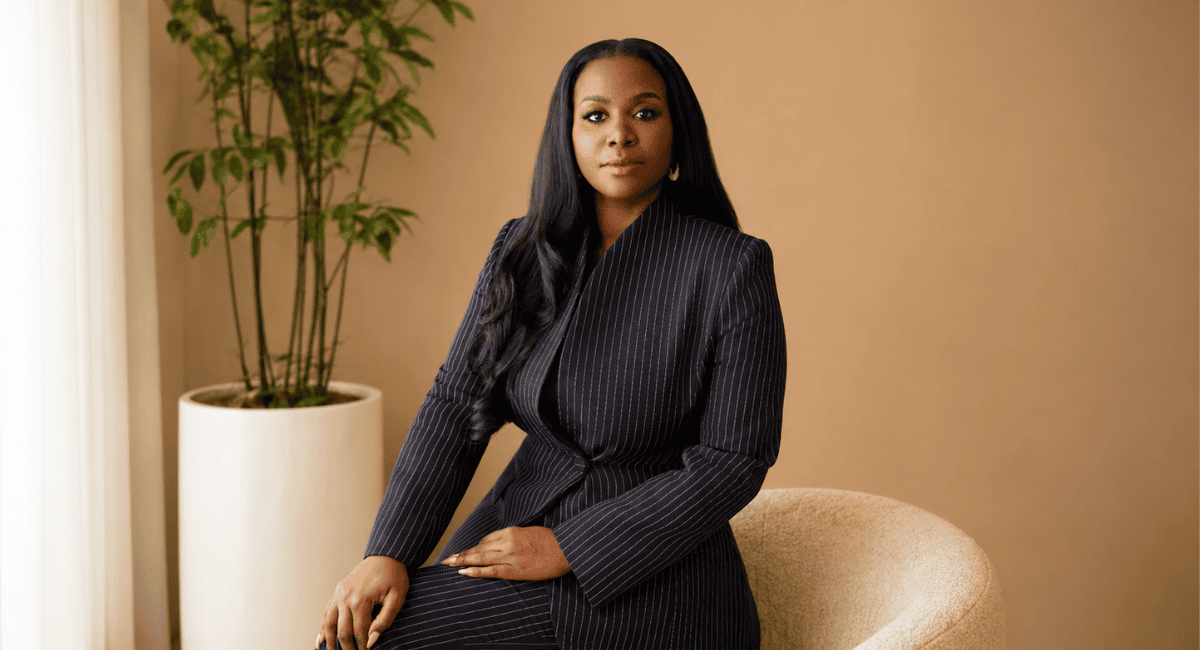
Few people are better placed to make that case than Gillian Darko, Group Vice President of Strategy at Yellow Card, the pan-African crypto infrastructure firm that started as a retail trading app in 2019 and has since rebuilt itself into a business-to-business payments layer for banks, telcos and corporates.
In an exclusive interview with Technext, she laid out why she believes Africa isn’t just adopting stablecoins alongside the rest of the world but is quietly setting the pace.
Darko is careful not to treat stablecoins as a solution in search of a problem. “You also have to think about what the problem is that you wish to solve on the continent,” she said, pointing to fragmented ecosystems, thin liquidity and the sheer cost of moving money across African borders as the real drivers of adoption.
“There are a lot of problems across several different regions on how to move money efficiently,” she added, describing the current wave of interest as the moment those long-standing issues finally caught up with the technology built to solve them.
Darko put the global cross-border payments market at roughly $194.6 trillion today, rising to $320 trillion by 2030, with Sub-Saharan Africa remaining the world’s most expensive corridor, where, in her words, “banks are averaging 14.5% in fees.” On-chain crypto transactions in the region, she said, have grown from around $205 billion last year to roughly $300 billion this year, with stablecoins accounting for it.

For a corporate treasurer, the appeal is less about ideology and more about arithmetic. As Darko put it, if a business wants to make a cross-border payment, “you need to hold in one account currencies, then you have the local currency, then you have to also hold the foreign currency, then you have a nostro account as well, and then you have all the underlying compliance costs.”
Stablecoins, she argued, don’t erase that cost – “it is not completely free” – but it collapses several steps most businesses currently pay for separately.
A $2-4 trillion stablecoin market projection
Standard Chartered has projected the global stablecoin market could hit $2 trillion by 2028. Citigroup has gone further, forecasting $4 trillion by 2030. Asked whether those numbers are realistic, Darko didn’t flinch. “When I saw that figure, I actually smiled,” she said, recalling Citigroup’s projection landing a year earlier, “because we are heading in the right direction.”
Getting there, in her view, rests on three pillars.
First, regulatory coordination, not just individual countries writing rules, but jurisdictions actually talking to each other. “Institutions need certainty regarding who can issue stablecoins, the quality and custody of reserves, redemption rights, financial crime controls, bankruptcy treatment and the responsibility of intermediaries,” she said, pointing to Ghana’s and Rwanda’s early moves on passporting arrangements as a template, alongside sandbox initiatives from Ghana’s central bank and regulatory movement in Nigeria, Kenya and South Africa.
Second, what Darko calls the “orchestration layer”: the unglamorous plumbing of custody, transaction monitoring, local currency liquidity and API reporting that sits behind any settlement rail. “Often when people talk about stablecoins, they talk about the settlement layer; they ignore the plumbing, the orchestration layer,” she said. “Without that, what is your liquidity? Do you have any local currency? What are your reconciliation tools?”
Third, embedding stablecoins into products people already use, from merchant settlement and treasury management to remittances, a flow she pegged at around $96 billion for the continent, and tokenised capital markets. “The market must reach this,” she said. “It cannot reach this through just consuming stablecoins and wallets. It needs to do so through the full plethora of the offering.”
Why Africa? Why now?
Darko’s argument for African leadership leans on precedent as much as projection. Mobile money, she noted, was a proof of concept: “Africa, with its uniqueness, brought Momo. It looked at the difficulties around fragmented ecosystems. It created a system that was unique and solved the problems for Africans.” Stablecoins, in her words, are simply the next iteration of the same instinct.
The demographic case she made is familiar territory for anyone tracking UN and African Development Bank projections.
“By 2050, one in every four people on earth will be African, with the continent’s population expected to reach approximately 2.5 billion people. Africa already is home to 1.5 billion people today, making it the world’s second-largest population and fastest-growing major region.”
Layer a young, mobile-first population and consumer spending she expects to climb toward $16 trillion onto currency volatility and cross-border friction, and Darko bets that stablecoin usage scales with the population curve rather than against it.
She also pushed back gently on concerns, including ones raised by the World Bank, that stablecoin adoption in Nigeria could erode central banks’ grip on monetary policy. “Regulators right now are really focused on ensuring that there are regulatory sandboxes and structured pilots,” she said. “This allows them to actually observe how the product works and understand the flow of funds.”
Her preferred framing is cooperation over confrontation, with dollar-backed and locally-issued stablecoins “working together, not against each other”, so that, as she put it, “someone in Nigeria, Ghana, Kenya, South Africa and other parts of the continent should have accessibility to all forms in which to make payments.”
To illustrate how regulation builds trust rather than getting in the way, she reached for an analogy from her own commute: a taxi that broke down en route to a panel discussion in Kigali. “The traditional form of cross-border payment is you pick that taxi, you’ve paid them, and you hope that they will get you there,” she said.
Regulation, in her metaphor, is what ensures “the driver that is operating that vehicle has a licence, understands traffic rules, and understands and requires anti-money laundering so that every time a customer chooses that vehicle, they are comfortable that the regulation has reviewed them.”
For businesses weighing whether to get involved, Darko’s counsel was pointedly unglamorous. “It’s very important what the problem is and what the solution you wish to solve is,” she said, urging companies to first decide whether they want to issue a stablecoin or simply use existing rails to move money better; “those are very distinct.” From there, she said, “the institution needs to establish a measurable baseline. What does the process currently cost you? How long does settlement take? How many intermediaries are involved?”
On locally backed stablecoins pegged to African currencies rather than the dollar, she was candid about the limits, suggesting that “the central banks should work together as a whole ecosystem”. Regulatory fragmentation and inconsistent consumer demand across markets, she said, mean the idea remains more discussion than deployment for now; “there’s a lot of moving parts to it,” requiring deeper collaboration between central banks and market participants before it goes anywhere.
Yellow Card’s own pivot, from a consumer trading app to infrastructure serving banks and fintechs, mirrors the shift Darko describes across the industry. “As the market matured, the larger need became infrastructure,” she said of the company’s decision to shut down its retail app and focus on B2B. Whether the wider market actually reaches Standard Chartered’s $2 trillion marker by 2028 remains to be seen.
But on the evidence Darko presented, from regulatory sandboxes to a demographic wave few other regions can match, Africa’s stablecoin story looks less like a bet on the future and more like a continuation of a pattern the continent has run before.
As she put it, closing the conversation: “Stablecoins are a settlement layer. AI is also going to be the intelligence layer; it’s actually going to continue to move us in a direction to speed our growth even further.”
