



For six years, Grey built a cross-border payments engine for African freelancers and remote workers largely by leaning on North American money services registrations and local banking partners. Same company. Days after unveiling Paycheck, its salary product, the Y Combinator-backed fintech has secured regulatory approval from the Central Bank of Nigeria (CBN) to operate as an International Money Transfer Operator (IMTO) to lock in the Nigerian corridor.
The regulatory approval authorises Grey to facilitate inbound international money transfers directly into Nigeria, expand its connections to international payment corridors and cover person-to-person (P2P), business-to-person (B2P), and business-to-business (B2B) transactions. Announced in a statement shared with Technext today, the greenlight enables the San Francisco-headquartered payment company to gain a formalised domestic foothold to compete for Nigeria’s personal remittance inflows, which the statement, citing World Bank data, puts at roughly $22.8 billion in 2025.
Commenting on the approval, Idorenyin Obong, CEO and Co-Founder of Grey, said, “Regulatory compliance is central to how we build and operate our financial services. As we expand across markets, it is important that our operations meet the requirements of the regulators responsible for overseeing them. Securing CBN approval to operate as an IMTO is an important step for Grey in Nigeria. It strengthens our ability to facilitate inbound international transfers and reflects our long-term commitment to building reliable financial infrastructure for individuals and businesses operating across borders.”
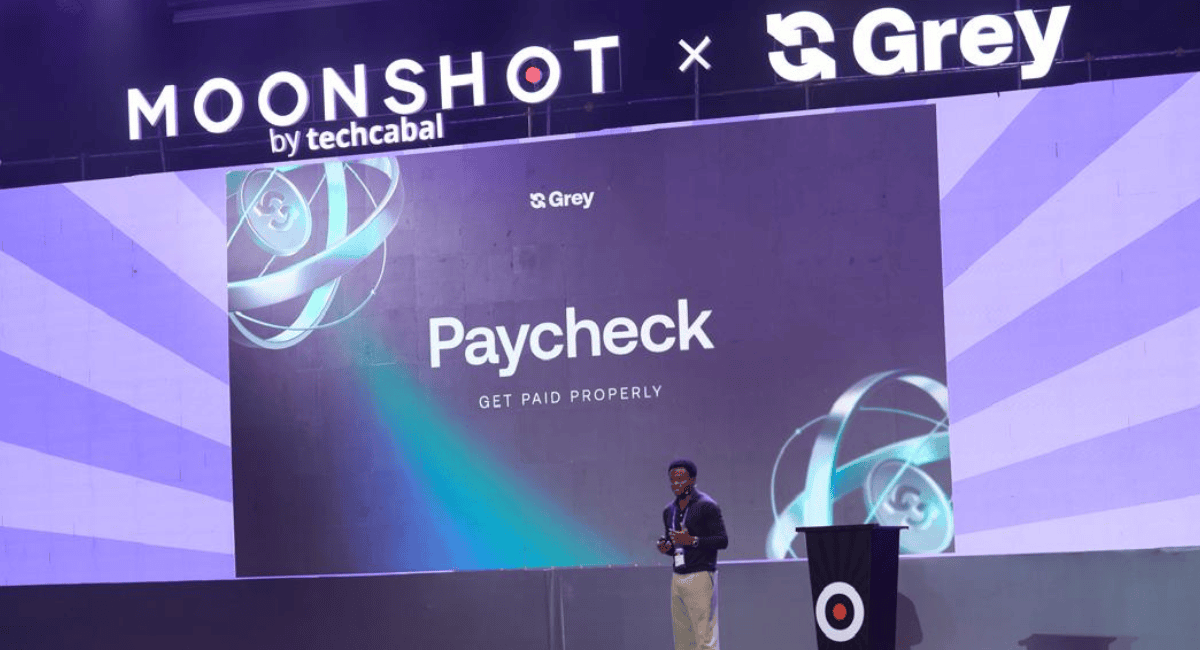
The licence arrives on the heels of Grey’s announcement at Moonshot on 29 October 2026 that it had crossed three million users and nearly $5 billion in processed payments, alongside a 170 per cent year-on-year surge in transaction volume.
Why owning the inbound rail matters now for Grey
To understand why direct CBN authorisation matters for Grey right now, one only has to look at how the foreign exchange trade has flipped for Nigerian remote workers over the past twenty months.
Between December 2021 and February 2024, leaving a $2,000 monthly remote salary untouched inside a Grey or rival Raenest wallet was the simplest inflation hedge. Over that period, the parallel market exchange rate slid from roughly ₦569 to ₦1,850 to the dollar, rewarding earners who held onto foreign currency. Since February 2025, that trade has reversed. By October 2026, the street rate had strengthened to between ₦1,370 and ₦1,390 per dollar, wiping out roughly 14 per cent in naira purchasing power for idle dollar holders at a time when local naira savings accounts yield up to 16 per cent, and the Nigerian Exchange (NGX) All-Share Index is up 59 per cent this year.
The numbers signal an urgent unit-economics challenge for cross-border fintechs. Because Nigerian remote professionals now convert their foreign salaries into naira within an hour of payday rather than parking balances in-app, platforms can no longer take passive dollar float for granted.
Grey’s first response was to launch Paycheck, a salary account for professionals earning in dollars, pounds, and euros that pays an introductory 3 per cent savings yield alongside higher transaction limits. Securing the CBN IMTO approval is the second half of that defensive play. By owning the regulated inbound settlement pipe into Nigeria, Grey can compress third-party payout friction and capture margin on the inbound leg even when users immediately liquidate their foreign earnings into local bank accounts.
The Nigerian authorisation plugs into a broader North American compliance stack that Grey uses to originate cross-border flows across more than 170 countries. In the United States, Grey is registered as a Money Services Business (MSB) with the Financial Crimes Enforcement Network (FinCEN). In Canada, the company is registered as an MSB with the Financial Transactions and Reports Analysis Centre of Canada (FINTRAC) and as a payment service provider under Canada’s Retail Payment Activities Act (RPAA).
Together, these regulatory credentials reflect Grey’s continued investment in building cross-border payment infrastructure within the regulatory frameworks of the markets in which it operates.
Beyond the compliance optics, the approval speaks directly to a structural bottleneck in Nigeria’s cross-border settlement rules. Since the apex bank overhauled its IMTO guidelines in January 2024, raising application fees to $1 million for foreign entities, mandating naira-only payouts for inbound remittances, and barring IMTOs from conducting outbound transfers or holding domestic deposits, unlicensed cross-border startups have faced heightened scrutiny over how their naira liquidity is sourced and settled.
