



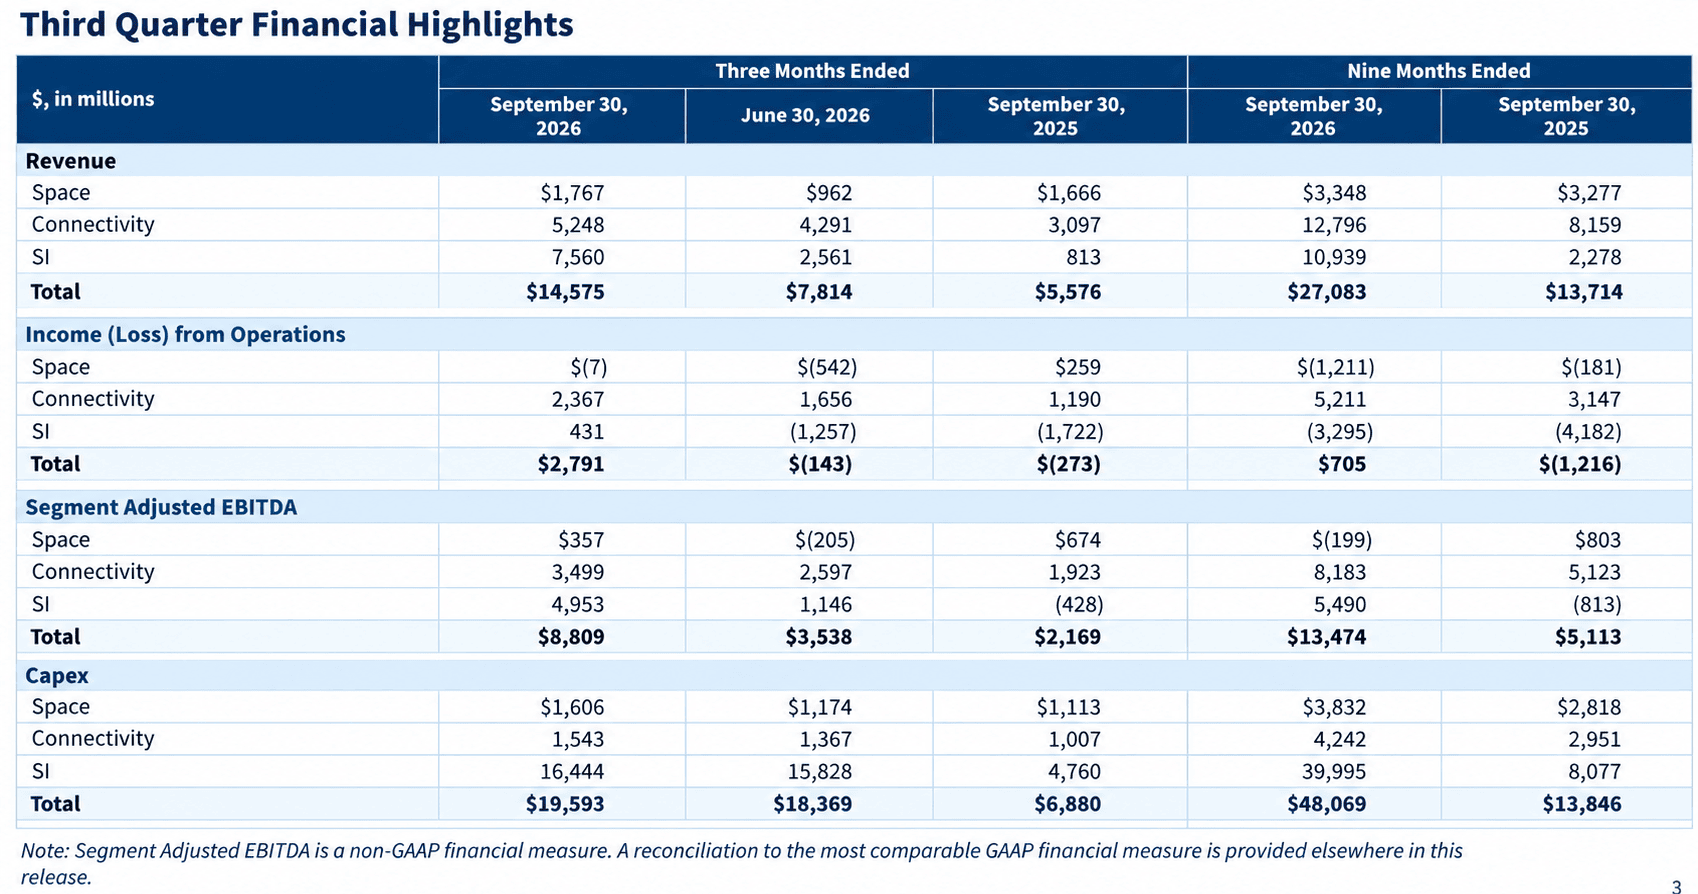
SpaceX’s third-quarter 2026 results, reported after the bell on October 20, mark the moment the company stopped being a rocket-and-satellite business with an AI side project and became an AI compute and software company that also happens to own the world’s dominant launch system and satellite broadband network. Revenue surged 161% year-over-year to $14.58 billion, comfortably ahead of the roughly $12.7 billion consensus estimate, with the newly branded Super Intelligence (SI) segment generating $7.56 billion of it, up a staggering 830% from a year earlier and, for the first time, more than half of total revenue.
Now trading under the ticker SPCX after its 2026 IPO, the company reported revenue of $14.58 billion, beating projections by roughly $1.7 billion. Adjusted EBITDA hit $8.81 billion against a consensus of about $6.6 billion, up 306% year-over-year, and the company swung to a GAAP net income of $4.4 billion from a $1.05 billion loss in the prior-year quarter, its first solidly profitable quarter since listing. Adjusted EPS of about $0.35 more than doubled Street expectations of $0.13–0.16.
The SI segment’s $6.7 billion in incremental revenue was boosted by three sources: the activation of major new cloud services agreements, the acquisition of coding platform Cursor (which closed mid-quarter and contributed $608 million), and accelerating adoption of the Grok model family, including the newly launched Grok Bot agentic system. Crucially, SI witnessed a dramatic turnaround after posting a $1.26 billion operating loss as recently as Q2; the segment turned operationally profitable at $431 million, even while absorbing $1.2 billion in Cursor-related stock compensation, and delivered $4.95 billion in adjusted EBITDA.
CFO Bret Johnsen offered a striking metric on the earnings call: at current pricing, new compute deployments are paying back in under a year, with compute pricing tracking “slightly above the high end” of 30–50 per watt. Nameplate capacity reached 1.7 GW at quarter-end, up from 0.6 GW a year ago, as construction continued on the COLOSSUS II facility.
Starlink still made strong contributions
Starlink, long SpaceX’s profit anchor, remains healthy. Connectivity revenue rose 69% year-over-year to $5.25 billion, with segment operating income up 99% to $2.37 billion. Consumer subscribers climbed to 13.6 million, up 89% from a year earlier, while ARPU ticked up 5% sequentially to $69. Starlink is now installed on more than 3,800 aircraft, and enterprise/government revenue jumped 91%.
The Space segment contributed $1.77 billion, up 6% year-over-year, highlighted by Starship Flight 14, the first revenue-generating Starship mission, which deployed 26 V3 Starlink satellites with roughly 10 times the downlink capacity of a Falcon 9 launch. SpaceX also announced Starbase, Louisiana, a next-generation spaceport targeting its first launch in 2029.
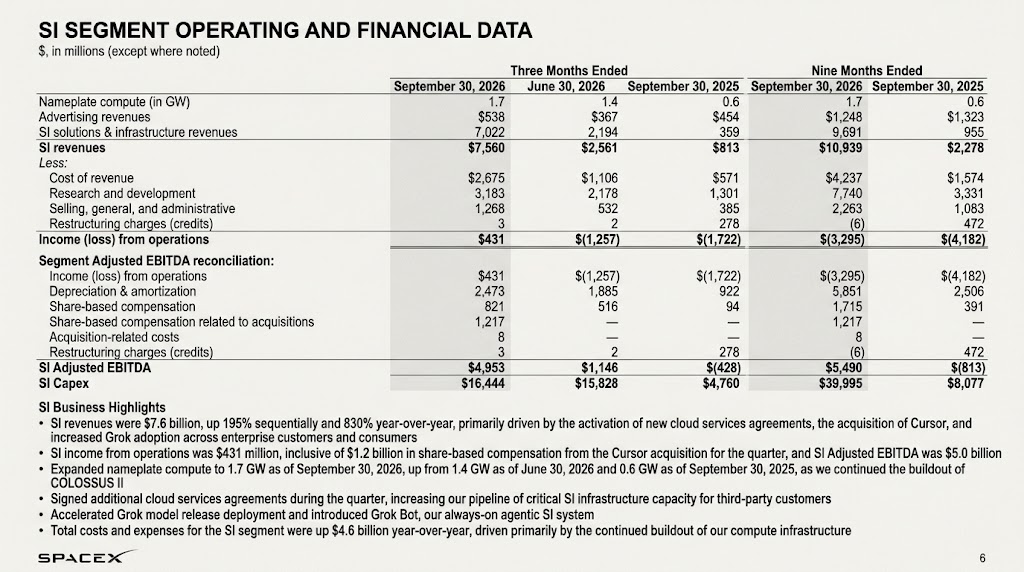
Meanwhile, it was not all uhuru; the quarter’s Capex totalled $19.6 billion, $16.4 billion of it in SI, and nine-month capital spending of $48 billion dwarfs operating cash flow of $13.1 billion. The $8.8 billion adjusted EBITDA figure also sits well above $2.8 billion in GAAP operating income, a gap worth monitoring. Still, roughly $90 billion in cash and marketable securities provides a formidable buffer.
SpaceX and Tesla merger talks
Musk confirmed on the call that both SpaceX and Tesla have formed special committees, composed of independent directors, formed at shareholder request, to explore a merger. Because Musk is a conflicted party in both companies, he cannot participate in the discussions. He was characteristically calibrated: “I don’t think we should necessarily assume a SpaceX and Tesla merger is a certainty. And I think that would be overstating it. Do I think it would be a good idea? Yes.”
The strategic logic, as Ark Invest frames it, is a combined entity generating $3.8 trillion in sales by 2031, with Tesla’s robotaxi cash flows funding SpaceX’s orbital data centres and SpaceX’s compute serving as the planning layer for Optimus deployments. But governance hurdles are real: any deal would require approval from over 50% of all Tesla shares voting yes.

Musk’s guidance will fuel the debate. He projected annual recurring revenue of $500 billion to $1 trillion by the end of 2027, numbers that annualise to $55 billion-plus in 2026 but imply a growth trajectory no public company has ever sustained.
The SpaceX Q3 earnings call revealed a genuinely historic quarter. The SI segment’s 830% growth validates the SpaceXAI restructuring; the first profit validates the operating model; the merger committees validate months of speculation. The risk, capital intensity, customer concentration in AI compute, and governance complexity of merging two Musk-controlled companies remain substantial. But after Q3, the burden of proof has shifted decisively to the sceptics.
