



A business can be built in Lagos today and have customers in Ghana, the UK, the US and Kenya within weeks. The internet has made that part easy, and getting paid by all those customers is another story.
A founder may have to deal with different payment providers, currencies, banks, foreign exchange rules, compliance requirements and settlement timelines just to get money from a customer to the business account. For large companies, there are treasury teams and finance departments to handle this. For a small internet business, it can become a problem the founder has to figure out personally.
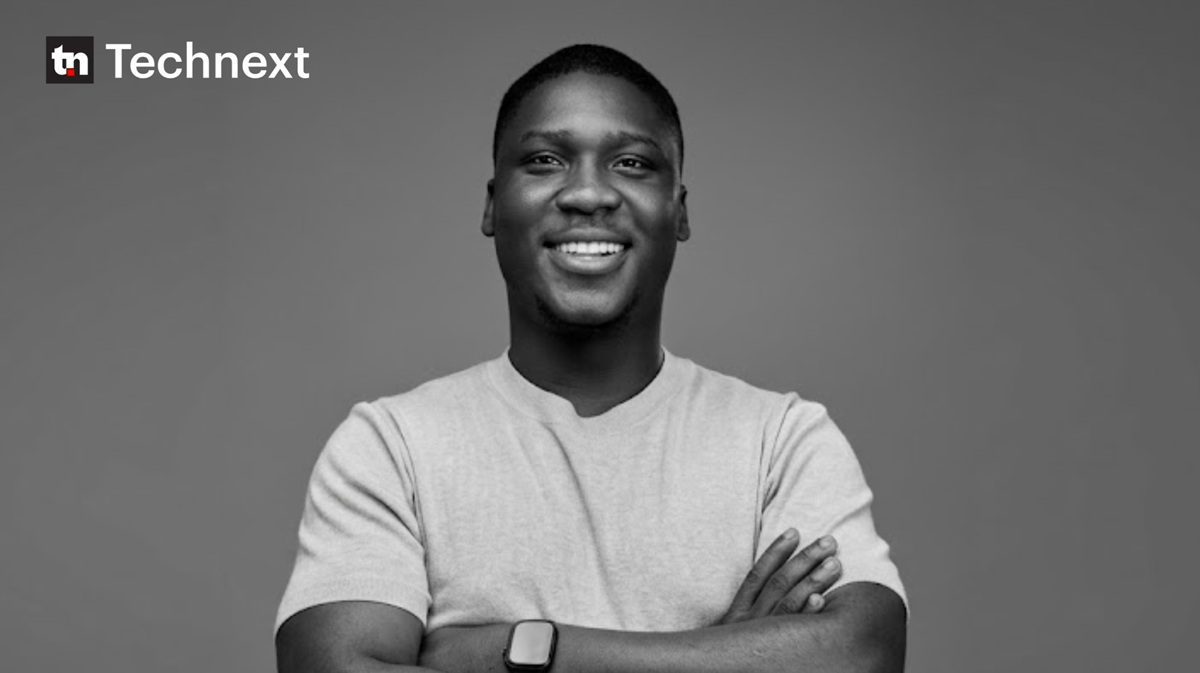
Bolu Dada, co-founder of payments infrastructure company Bachs, has spent years dealing with that problem. Before Bachs, Dada says his earlier company, Syncgram, helped hundreds of educators and internet entrepreneurs accept payments from customers around the world and processed more than $2 million in subscriptions.
That experience changed how he looked at payments. “The way people build businesses has changed much faster than the financial system supporting them,” Dada told Technext.
His point is simple. A business can be global from the moment it launches, but the financial system behind it is still largely organised around countries, banks and separate payment networks. “The payment experience should be much simpler,” he said. “You should be able to focus on running your business, not spend so much time figuring out how your money moves.”
The real problem starts after the customer clicks “Pay”
It is easy to think of a payment as the moment a customer enters their card details or approves a bank transfer, but that is only the beginning. Behind that transaction are several systems that have to work together. The payment has to be authorised, checked for fraud, converted into the right currency where necessary, settled and eventually made available to the business.
When the customer and the business are in different countries, more layers can appear. Dada believes this is where much of the problem lies.
For African businesses trying to sell globally, one of the biggest challenges is not simply accepting a payment. It is convincing financial institutions and payment companies that the business and its transactions are safe. “Ultimately, where you’re building your business shouldn’t determine how much access you have to the global payment system,” he said.
That risk problem matters because payment companies cannot simply process everything that comes their way. They have to protect themselves and their customers from fraud, money laundering, stolen cards and other forms of financial crime. The result is a difficult balance. Stronger controls can protect the system, but they can also make it harder for legitimate businesses in markets perceived as higher risk to access global payment networks.
Then there is the cost of moving the money.
The World Bank says sending $200 to Sub-Saharan Africa costs about 8.78% on average, compared with 6.49% globally, based on its 2025 data. The World Bank has also pointed to limited competition and weak cross-border interoperability as reasons remittances remain expensive.
Similar read: Should fintechs have upgraded their apps for the Dangote IPO? Orezi Mena says building for the rush could be a costly mistake
For a person sending money home, that is already frustrating. For a business receiving hundreds or thousands of payments across different countries, the complexity can quickly become a much bigger financial and operational problem. Dada argues that the middle of the market is particularly underserved.
Large companies can afford treasury teams to manage currencies, liquidity and international settlements. Consumers have remittance services built specifically for sending money across borders. But what about the founder running a small online business from Lagos who has customers in five countries?
That founder should not need to become a treasury expert just to collect revenue. This is also why Dada says building Bachs has taught him something he did not fully appreciate at the beginning. “One of the biggest things we’ve realised is that we’re much more of a treasury business than we initially thought,” he said.
Treasury, in simple terms, is the part of a business that manages its money: where it sits, which currency it is held in, when it arrives, how it is moved and how much it costs to move it. For an international internet business, those questions can be just as important as the payment button itself.
Stablecoins are becoming part of the plumbing
Stablecoins are becoming a bigger part of cross-border payments, and Nigeria is a major example. The IMF estimates that Nigeria received about $59 billion in crypto-asset inflows between July 2023 and June 2024, while stablecoins made up more than 65% of the country’s crypto inflows in 2024. Nigeria also accounted for about 60% of stablecoin inflows into Sub-Saharan Africa between late 2019 and early 2025.
For Dada, that growth shows why stablecoins are becoming useful for businesses moving money across borders. “I don’t know if we could build Bachs the way we’re building it today without them,” he said.
Unlike traditional international transfers, which can pass through several banks and require businesses to manage different currencies and liquidity, stablecoins such as USDT and USDC can move value across blockchain networks almost instantly.
But they are not a complete fix. The IMF says stablecoins can make cross-border payments faster and cheaper, while also creating risks around regulation, financial stability and the growing use of dollar-linked assets outside the traditional banking system.

Dada also sees room for local-currency stablecoins such as cNGN, particularly as African businesses deal with multiple currencies and payment systems. The bigger challenge, however, is making these systems work together.
“We’re still early,” Dada said. “We’re moving towards a financial system that’s much more interoperable and programmable than what we have today.” That may be the real test for the next generation of payment infrastructure: not simply moving money faster, but making it easier for businesses to move money across borders without having to understand all the machinery underneath.
Also read: Nigeria’s fintech boom drew $5bn from U.S. investors, Consul General says
